
Independent Insurance Broker Michael Doty Announces Homeowner Outreach in Connecticut and Virginia
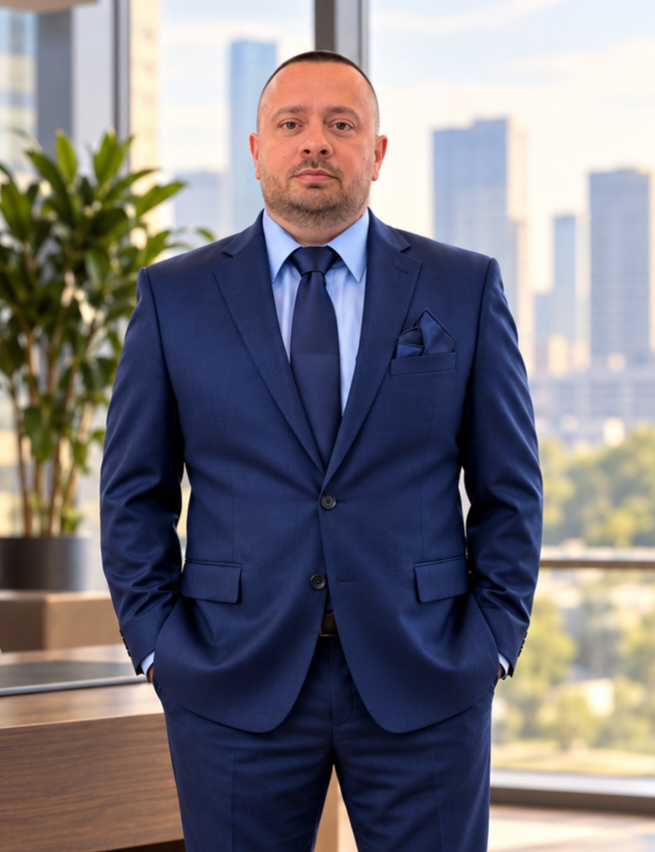
Michael Doty, Independent Insurance Broker
Planned direct-mail initiative invites homeowners to compare insurance options, review rebuilding coverage and prepare for renewal.
An estimated premium is a conversation starter, not a promise. Once we learn more about the property and the homeowner's situation, we can prepare a real comparison.”
GLEN ALLEN, VA, UNITED STATES, November 1, 2026 /EINPresswire.com/ -- Independent insurance broker Michael Doty is announcing a targeted homeowner education and outreach initiative in Connecticut and Virginia designed to help residents evaluate their homeowners insurance before the next renewal. The planned campaign will send approximately 1,000 personalized mail pieces each month, split between the two states, during an initial four-month period.— Michael Doty, Independent Insurance Broker
The initiative will focus on Southington, Connecticut, and selected Virginia neighborhoods, combining property-based preliminary estimates with invitations to request an individualized insurance review. Homeowners who respond will have an opportunity to discuss available carriers, dwelling coverage, deductibles and other policy terms rather than relying solely on the premium shown on a renewal notice.
“Homeowners often renew because the paperwork arrives and life gets busy,” said Doty. “I want them to know they have options. My job is to compare those options, explain the differences and help them make an informed decision about what fits their home and budget.”
The outreach comes as homeowners across the country contend with higher insurance expenses. An October 2026 NerdWallet analysis found that modeled home insurance premiums for a typical U.S. homeowner rose 24% between early 2023 and early 2026. The report also showed that the effects vary by home age, location and other characteristics.
A September 2026 report from Intercontinental Exchange offered another perspective on shopping. Among homeowners in its mortgage data who changed private insurance carriers, annual insurance costs declined an average of 6.6% over the preceding year. Homeowners who remained with their existing carrier experienced an average 10.4% increase. These are broad research findings, not forecasts of savings for any individual household.
Doty's approach begins with an estimated rebuilding value based on available property information, including square footage and construction year. Those initial figures help create a relevant starting point for each mailed invitation, but they are not a carrier-approved replacement-cost assessment or a guaranteed insurance quote.
An accurate premium depends on information a homeowner provides and on each insurer's underwriting rules. Relevant factors may include roof age and condition, prior claims, insurance-based credit information where permitted, construction details, selected deductibles and coverage limits. A thorough comparison also considers the scope of protection, not merely the lowest advertised price.
“An estimated premium is a conversation starter, not a promise,” Doty said. “Once we learn more about the property and the homeowner's situation, we can prepare a real comparison. Sometimes the biggest value is a lower premium. Other times it is discovering a coverage issue that needs attention.”
One frequent source of confusion is the difference between a home's market value and its replacement cost. Market value can reflect land, neighborhood demand and broader real estate conditions. Dwelling replacement cost focuses on what it could take to rebuild the structure following an insured loss. As the National Association of Insurance Commissioners explains, those figures are not interchangeable.
Doty also encourages homeowners to review how policies handle roof losses, wind and hail deductibles, personal property, additional living expenses and liability protection. Coverage provisions and eligibility vary by insurer and state. A cheaper policy may not represent a better choice if it leaves meaningful protection gaps or shifts unexpected expenses to the customer.
The proposed letters will invite recipients to request a no-obligation comparison through Doty's independent brokerage. The comparison is informational and entirely optional. Rather than representing only one insurer, the agency can evaluate options available through its appointed markets, subject to eligibility and underwriting approval. Doty says his goal is to make the process accessible, educational and straightforward.
“People should feel comfortable asking why their premium changed, what their deductible really means, and whether their home is insured appropriately,” Doty said. “An insurance decision should be made with confidence, not confusion.”
About Michael Doty
Michael Doty is an independent insurance agent and broker serving clients across multiple states. Through an education-led approach, he helps homeowners and drivers compare coverage options, understand policy details and make informed insurance decisions. His guiding message is “Compare your options. Choose with confidence.” For information or to request a no-obligation coverage review, visit mikeismybroker.com.
Michael Doty
MICHAEL DOTY
+1 860-458-4321
Visit us on social media:
Facebook
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
